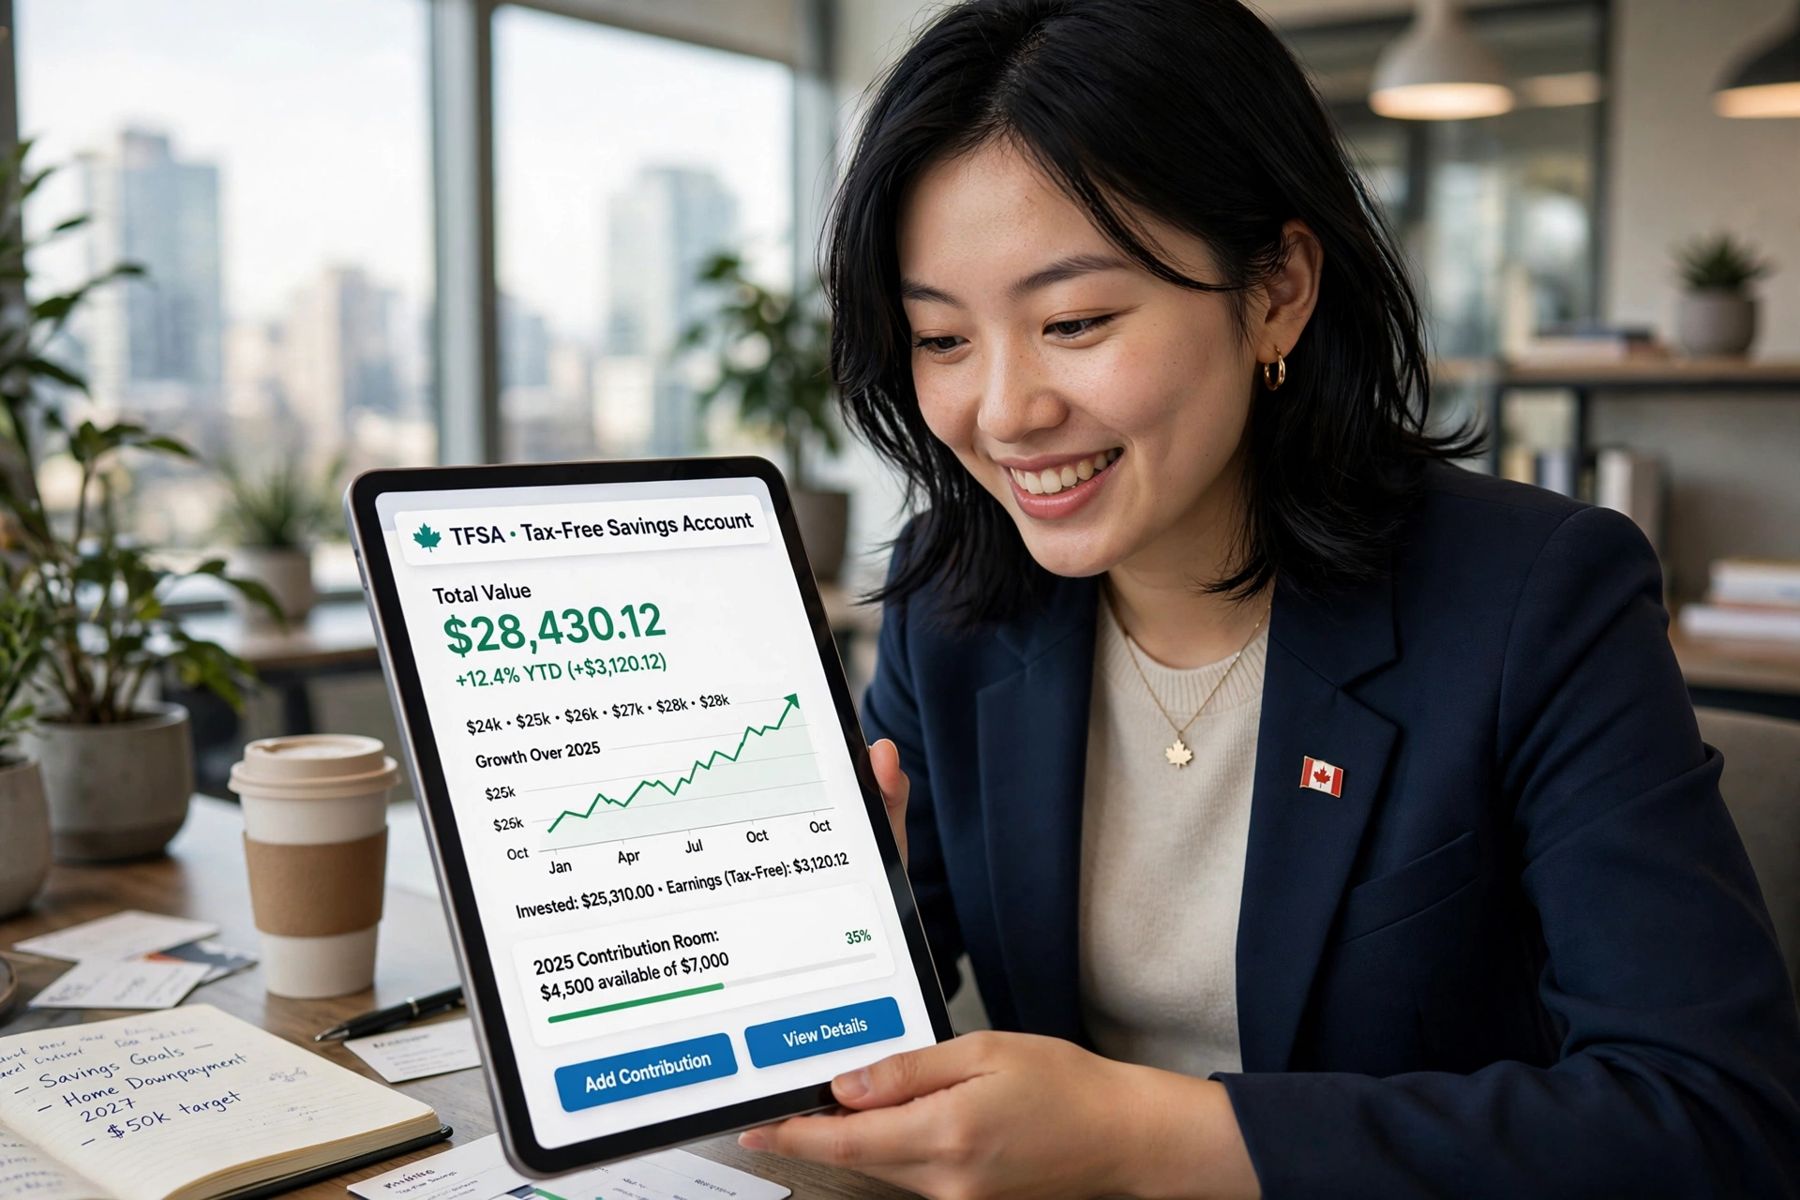
Canada gives you three powerful savings accounts — the TFSA, RRSP and FHSA. Each one saves tax in a different way. Here are the 2026 limits and a simple way to decide where your next dollar should go.
2026 at a glance
- TFSA: the 2026 annual limit is $7,000. If you've been eligible since 2009 (age 18+ and a Canadian resident) and have never contributed, your total room in 2026 is $109,000.
- RRSP: you can contribute 18% of last year's earned income, up to a 2026 maximum of $33,810, minus any pension adjustment. Unused room carries forward.
- FHSA: first-time home buyers can contribute $8,000 a year, up to $40,000 in total. Up to $8,000 of unused room can be carried forward to the next year.
Your exact room is shown in your CRA My Account and on your Notice of Assessment. Over-contributing to any of these accounts triggers a penalty tax, so check before you deposit.
TFSA — tax-free growth, total flexibility
You don't get a tax deduction when you put money in, but everything it earns — interest, dividends, growth — is tax-free, and so are withdrawals. Money you take out is added back to your room on January 1 of the following year.
Best for: emergency funds, medium-term goals, and anyone in a lower tax bracket today.
RRSP — a tax refund now, tax later
Contributions are deducted from your income, which can mean a refund. Investments grow tax-sheltered, but withdrawals are taxed as income — ideally in retirement, when your tax rate may be lower. Contributions made in the first 60 days of a year can count for the previous tax year.
Best for: higher earners saving for retirement. The Home Buyers' Plan also lets you borrow from your RRSP for a first home.
FHSA — the best of both, for your first home
The FHSA combines the two: contributions are tax-deductible like an RRSP, and a qualifying withdrawal to buy your first home is tax-free like a TFSA. Room only starts building once you open the account, so it pays to open one early even if you can't contribute much yet. If you don't buy a home, the money can usually be moved to your RRSP without using RRSP room.
Best for: anyone who hasn't owned a home recently and may buy one in the next 15 years.
So where should your next dollar go?
- Planning to buy a first home? Start with the FHSA.
- Higher income and saving for retirement? The RRSP refund is hard to beat — consider putting the refund into your TFSA.
- Lower income, or you may need the money before retirement? The TFSA usually wins.
Many families use all three. The right mix depends on your income, timeline and goals — and on the investments you hold inside the account.
Official details: TFSA (CRA) · RRSP (CRA) · FHSA (CRA). You can also read our TFSA, RRSP and FHSA pages, or book a free review.
This article is general information, not personal financial, tax, legal or immigration advice. Rules and limits change — confirm details with an advisor or the official source before you decide.